
Super.com-Cash Advance, Travel
- Rating
- 4.5
- Downloads
- 1.00M
- Content Rating
- Everyone
Super.com-Cash Advance, Travel - Screenshots
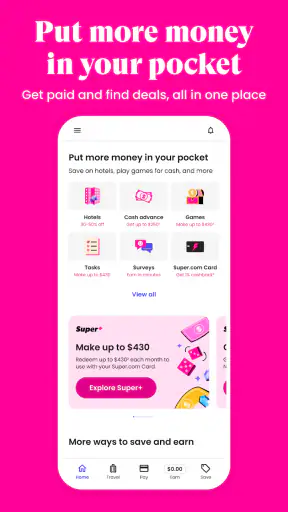
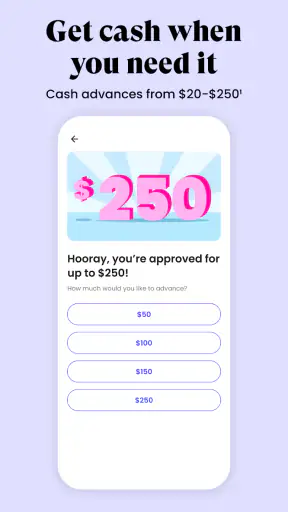
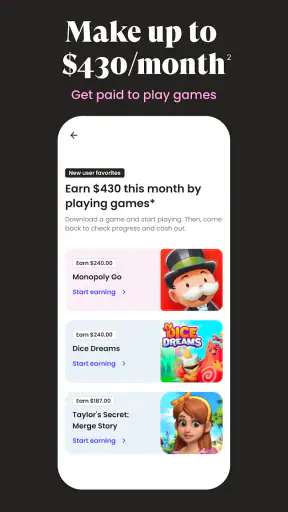
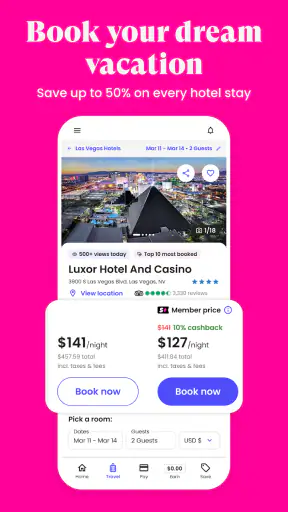
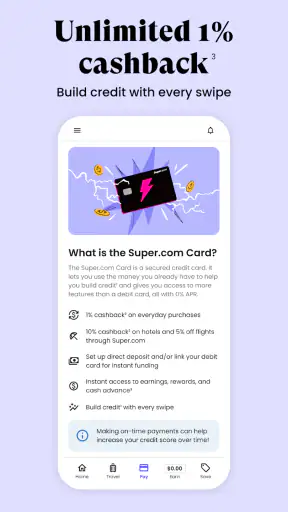
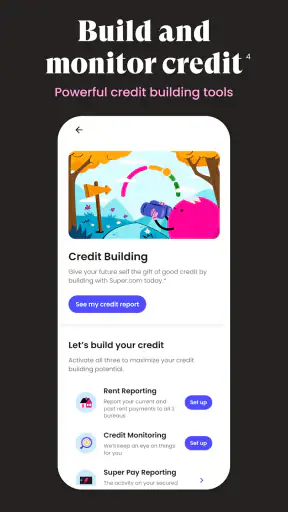
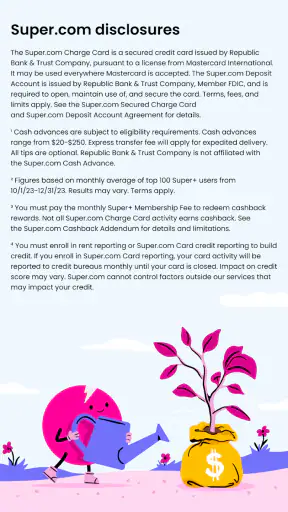
Pros
- Cash advances can help cover urgent expenses before payday.
- Travel booking tools and deals are available in the same app.
- The interface is generally straightforward for managing account features.
- Users can compare selected travel options without switching apps.
- Repayment details are presented before confirming an advance.
Cons
- Advance availability and limits may depend on eligibility and account history.
- Fees or membership costs can reduce the value of a cash advance.
- Late repayment may affect access to future advances or add costs.
- Travel prices and availability can change before a booking is completed.
- Some features may be restricted by location or supported payment methods.
Super.com-Cash Advance, Travel - Description
- App Name
- Super.com-Cash Advance, Travel
- Package Name
- com.snaptravel.core
- Developer
- Super (previously SnapTravel)
- Category
- Finance
- Last Updated
- Jun 27, 2019
- Version
- 14.10.8
I approached Super.com-Cash Advance, Travel as a practical finance app rather than as a single-purpose budgeting tool. Its promise is broad: it brings money-saving ideas, earning opportunities, travel-related services, and cash access into one place. That combination can be useful when I want to handle several everyday money tasks without moving between a collection of separate apps, but it also means the experience deserves a closer look than a simple “install and save” recommendation.
Developed by Super, previously known as SnapTravel, this free app sits in the finance category and is available for Everyone. It has built a substantial audience, with more than a million installs and an average rating of 4.5 from roughly 31 thousand ratings. Those figures suggest that the general concept works for many people, although they do not remove the need to check each offer, condition, or financial decision carefully.
How Super.com feels in everyday use
The first impression: broad rather than narrowly focused
What stands out immediately is the attempt to combine several money-related activities in one destination. Instead of opening one app for travel, another for savings, and another for short-term financial help, I can start with the same Super account and explore the available sections from there. That is convenient for people who prefer a central dashboard, especially when a trip or an unexpected expense makes several financial tasks overlap.
The trade-off is focus. A dedicated travel app usually makes searching, comparing, and organizing a trip feel more direct. A dedicated budgeting app may offer a clearer view of spending habits. Super.com-Cash Advance, Travel is trying to serve both kinds of needs, along with earning and saving, so I would not expect every area to feel as deep or specialized as an app built for only one job.
I found the app easiest to understand when I approached it with one specific goal. For example, I might open it to investigate travel savings first, then review whether another money feature is relevant. Browsing without a purpose can make a multi-service finance app feel busier than necessary. My practical advice is to decide what you are trying to accomplish before tapping through every available option.
Speed expectations and the value of a clear starting point
For a finance app, perceived speed is not only about how quickly a screen appears. It is also about how quickly I can understand what to do next. Super.com-Cash Advance, Travel benefits from a task-led approach: I get more value when I move straight toward a travel search, a savings opportunity, or a cash-related section instead of treating the home screen as something to study indefinitely.
On a capable device with a stable connection, I would expect ordinary navigation to feel reasonably straightforward. Travel and financial services naturally depend on current information, account details, and online responses, so some actions may take longer than moving between static screens. That is not automatically a problem, but it does mean I would avoid starting an important booking or money request while rushing through a poor connection.
A useful habit is to pause and read the details before confirming anything. Fast navigation can create a false sense that every choice is equally simple. In reality, a travel offer and a financial advance have very different consequences. The app may help me reach both from the same place, but I still need to slow down when the action involves repayment, eligibility, dates, or a total cost.
A realistic everyday scenario
Imagine that I am planning a weekend away while trying to keep the rest of the month under control. I could use Super.com-Cash Advance, Travel to investigate travel-related savings, compare the available arrangement with the price I see elsewhere, and then look at the app’s other money tools if an unexpected bill appears. The convenience comes from keeping these steps together instead of switching contexts repeatedly.
However, I would not treat the app as permission to stretch my budget. If a cash advance is available, I would first write down the bill amount, my next expected income, and the repayment impact. The app can make access easier, but an easier application process does not make borrowing free of consequences. This is one of the most important distinctions between convenience and genuine affordability.
For travel, I would also compare the complete cost rather than focusing on an attractive starting figure. Dates, changes, extras, and the final checkout amount matter more than the first result. Super’s travel background may make the travel side particularly relevant, but I would still use the app as one comparison point rather than assuming it is automatically the cheapest or best fit.
What happens during heavier use
The app’s broad design becomes more demanding when I use several areas in one session. Looking through travel choices, returning to the main money dashboard, reviewing savings possibilities, and checking account-related information creates more transitions than a single-purpose application would. Even if the device handles the interface well, the mental load can be higher because each section asks a different kind of decision from me.
That is where a simple workflow helps. I prefer to finish one objective before beginning another, save any information I need, and then return to the main screen. This reduces the chance of confusing a travel promotion with a financial product or forgetting which terms applied to which action. It also makes the app feel less cluttered during a longer session.
Heavy use can also mean returning to the app repeatedly over several days. A travel search may be exploratory, while a money-related task may be time-sensitive. I would keep a separate note of important dates, expected costs, and repayment commitments rather than relying on memory from a previous visit. That is not a criticism of the interface; it is a sensible safeguard when one app covers both shopping-style decisions and personal finance.
Stability and what reliability means here
Reliability in this app has two layers. The first is technical: screens should open, navigation should remain understandable, and a session should not leave me wondering whether an action went through. The second is financial and practical: the information shown at the moment of decision must be read carefully, and I need to know what I am agreeing to before continuing.
I would be more forgiving of a brief loading pause than of an unclear confirmation state. If an important action appears slow, I would avoid tapping repeatedly. Instead, I would wait for the result, check whether the screen changed, and confirm the account or transaction status before trying again. Repeated taps are especially unhelpful when money or a reservation may be involved.
Super.com-Cash Advance, Travel has the advantage of being an established app with a sizable user base, but popularity is not a guarantee that every individual experience will be perfect. Network quality, account circumstances, and the specific service being used can all affect how dependable the session feels. My view is that the app is best treated as a useful financial interface, not as a substitute for checking records and keeping personal documentation.
Recovery matters as much as normal operation. If I lose a connection halfway through a process, I would reopen the relevant section, look for a clear status, and avoid assuming that an unfinished-looking screen means nothing happened. For a travel action, I would look for confirmation details. For a money action, I would check the account information and any available record before retrying. This cautious recovery routine is more valuable than chasing speed.
Device constraints and the current software baseline
The current version is 14.10.8, and the app requires at least iOS or Android version 10, depending on the platform. That minimum makes it accessible to many relatively modern phones, but anyone using an older device should check the operating system before planning around the app. A compatible phone is only the starting point; available storage, background activity, and connection quality can still shape the experience.
I would not describe this as an app that should require an unusually powerful handset simply because it belongs to finance. Most of the demanding work is likely connected to online content and service responses rather than elaborate graphics. Still, a phone that struggles with other current apps may also make transitions feel less comfortable here, particularly during a long session involving travel browsing and account screens.
Resource demands are also practical rather than purely technical. A travel-heavy session may involve repeated online loading, while financial sections require attention and secure handling. I would use a reliable connection, keep the phone updated enough to meet the minimum requirement, and avoid managing sensitive tasks on a device that is nearly full or behaving unpredictably. These habits improve confidence even when the app itself is working normally.
The Everyone content rating is helpful for general accessibility, but it should not be mistaken for a recommendation that every financial feature suits every person. Age suitability and financial suitability are different questions. A younger or inexperienced user may still need an adult to explain borrowing, repayment, travel conditions, or the difference between a discount and a lower total cost.
Saving and earning: useful, but not automatic
The saving and earning angle is appealing because it gives the app a purpose beyond emergency access or travel shopping. I like the idea of checking whether an ordinary purchase or planned trip can fit into a broader money routine. The key is to treat these sections as opportunities to investigate, not as guaranteed improvements to my finances.
When I see a potential saving, I would compare it with my normal alternative and ask whether I would make the purchase anyway. A discount on something unnecessary is still spending. Likewise, an earning opportunity deserves a look at the effort, timing, and actual usefulness to me. The most disciplined approach is to measure the result against my original plan rather than counting every displayed offer as money gained.
One non-obvious advantage of having these tools beside travel features is that I can evaluate the whole trip budget in one sitting. I can consider the room or travel cost, then think about how the purchase fits into upcoming bills and savings goals. That broader view is more useful than chasing a small reduction while ignoring the overall expense.
Cash advances require the most careful judgement
The cash advance side is where I would be most cautious. It can be attractive when a bill arrives before payday, and a familiar app may feel less intimidating than searching for a separate provider. But the right question is not simply whether I can obtain money quickly. I need to understand the total repayment obligation, timing, and whether the next income cycle can comfortably absorb it.
I would only consider this route for a defined short-term gap, with a written repayment plan and a clear reason for the expense. I would skip it if I was already using one advance to cover another, if the bill was discretionary, or if repayment would leave too little for essentials. In those situations, a conversation with the bill provider, a conventional bank option, or a trusted local support service may be more appropriate.
This is also an area where the app should not replace comparison. The convenience of applying inside a familiar interface may save time, but I would compare the complete obligation with other available choices and read every condition shown before accepting. A quick path to funds is useful only when the repayment path is equally clear.
Travel tools compared with usual alternatives
Against a traditional travel app, Super.com-Cash Advance, Travel’s main advantage is consolidation. I can explore travel while keeping saving and money-related considerations close at hand. That is especially convenient for someone who wants to connect a trip with a wider financial plan rather than book first and think about affordability later.
A dedicated travel service may still be better when I need the deepest search controls, a highly specialized loyalty system, or a very detailed itinerary workflow. Similarly, a spreadsheet or budgeting app may give me a clearer long-term picture of income and expenses. Super is strongest when convenience across categories matters more than having the most specialized tool in each category.
I would also compare final prices and conditions manually. The first attractive travel result is not necessarily the best value once dates, flexibility, and extras are considered. The app can be a useful starting point, but my final decision should be based on the complete arrangement and how it fits my available money.
Who should use it, and who should skip it
I think Super.com-Cash Advance, Travel suits people who want one finance-oriented app for several connected tasks: exploring travel, looking for ways to save, considering earning options, and handling a short-term money need with care. It is also a reasonable choice for users who dislike maintaining several separate apps and are comfortable checking details for themselves.
I would be less enthusiastic for someone who wants a pure budgeting application with detailed long-term tracking, a specialist travel planner, or a simple bank account experience without additional offers and services. It may also be the wrong choice for anyone hoping that a cash advance will solve a recurring income problem. In that case, the app’s convenience could encourage a cycle rather than fix the underlying issue.
People who prefer complete control over every financial category may find the all-in-one approach less satisfying than a small set of specialized tools. I personally see the broad scope as useful for discovery and convenience, but I would not let it replace a personal budget, a bank statement, or careful comparison shopping.
My performance verdict after weighing convenience against control
Super.com-Cash Advance, Travel is a capable idea for people who want saving, earning, travel, and short-term money tools gathered in one finance app. Its perceived speed should be judged by the online nature of the services it connects to, not by expecting every screen to behave like an offline calculator. With a compatible device and dependable connection, the experience should be most comfortable when I use one clearly defined task at a time.
The app’s broad design is both its strength and its main limitation. It reduces app switching, but it asks me to stay organized and resist impulsive decisions. The travel side can complement the money side, while the cash advance feature demands the highest level of caution. I would verify totals, read conditions, record important confirmations, and keep repayment plans separate from casual browsing.
With a free price and a mature release history dating back to June 27, 2019, it is easy to see why the app has attracted a large audience. My recommendation is measured rather than unconditional: try it if you value a connected financial toolkit, but keep a personal budget and compare important choices elsewhere. The best way to use Super.com-Cash Advance, Travel is as a convenient decision-making hub, not as a replacement for financial judgement.
FAQ
What is Super.com-Cash Advance, Travel, and what can I use it for?
Super.com is a financial and travel app that combines services such as cash advances, travel bookings, rewards, and other money-saving features in one place. Depending on your eligibility and location, you may be able to request an advance, compare or reserve hotels and flights, and access member benefits. Available features can vary by country, account type, and current promotional terms.
How does the Super.com cash advance work, and are there any fees?
The cash advance feature may allow eligible users to access part of their expected income before payday. Approval, advance limits, repayment dates, and eligibility requirements are determined by Super.com and may depend on account activity or other information. Before accepting an advance, carefully review the complete disclosure, including membership charges, express-transfer fees, optional services, repayment conditions, and any other applicable costs.
Is Super.com safe to use for financial information and travel bookings?
Super.com handles sensitive personal, payment, and financial information, so users should review its privacy policy, security practices, and permission requests before creating an account. Use the official Android or iOS store listing, enable device security, and avoid sharing login codes. Travel reservations should also be checked for supplier details, cancellation rules, taxes, and restrictions before payment.
Does Super.com require a subscription or membership payment?
Some Super.com features may be connected to a paid membership, trial period, or recurring subscription, while other services may be available without the same plan. The exact pricing and benefits can change, and eligibility may depend on your region. Read the checkout screen and membership terms carefully, especially the renewal date, cancellation procedure, refund policy, and whether a trial automatically converts into a paid plan.
What should I check before booking travel or downloading the app?
Before downloading or booking through Super.com, confirm that the app is available in your country and that the displayed travel prices include all taxes, fees, baggage costs, and restrictions. Check the provider’s cancellation and change policies, since discounted reservations may be nonrefundable. Also verify the app’s recent reviews, required permissions, customer-support options, and the terms for any rewards or promotional discounts.


